Agricultural credit & insurance
Verify crop, acreage, production potential and weather exposure throughout the season.
Underwriting Agent
Financial asset intelligence
Connect verified geospatial, weather, climate and domain evidence to origination, monitoring and portfolio decisions.
Portfolio intelligence
Cropin’s proven agricultural underwriting foundation expands into a common physical-risk layer for lenders, insurers, investors and governments.
Verify crop, acreage, production potential and weather exposure throughout the season.
Monitor basin stress, land-use change, canopy condition, wildfire and carbon integrity.
Assess vegetation, flood, erosion, subsidence and climate risk around assets and corridors.
One decision layer
Standardize physical-risk signals without flattening the domain context that makes each exposure different.
01 / IN PRACTICE
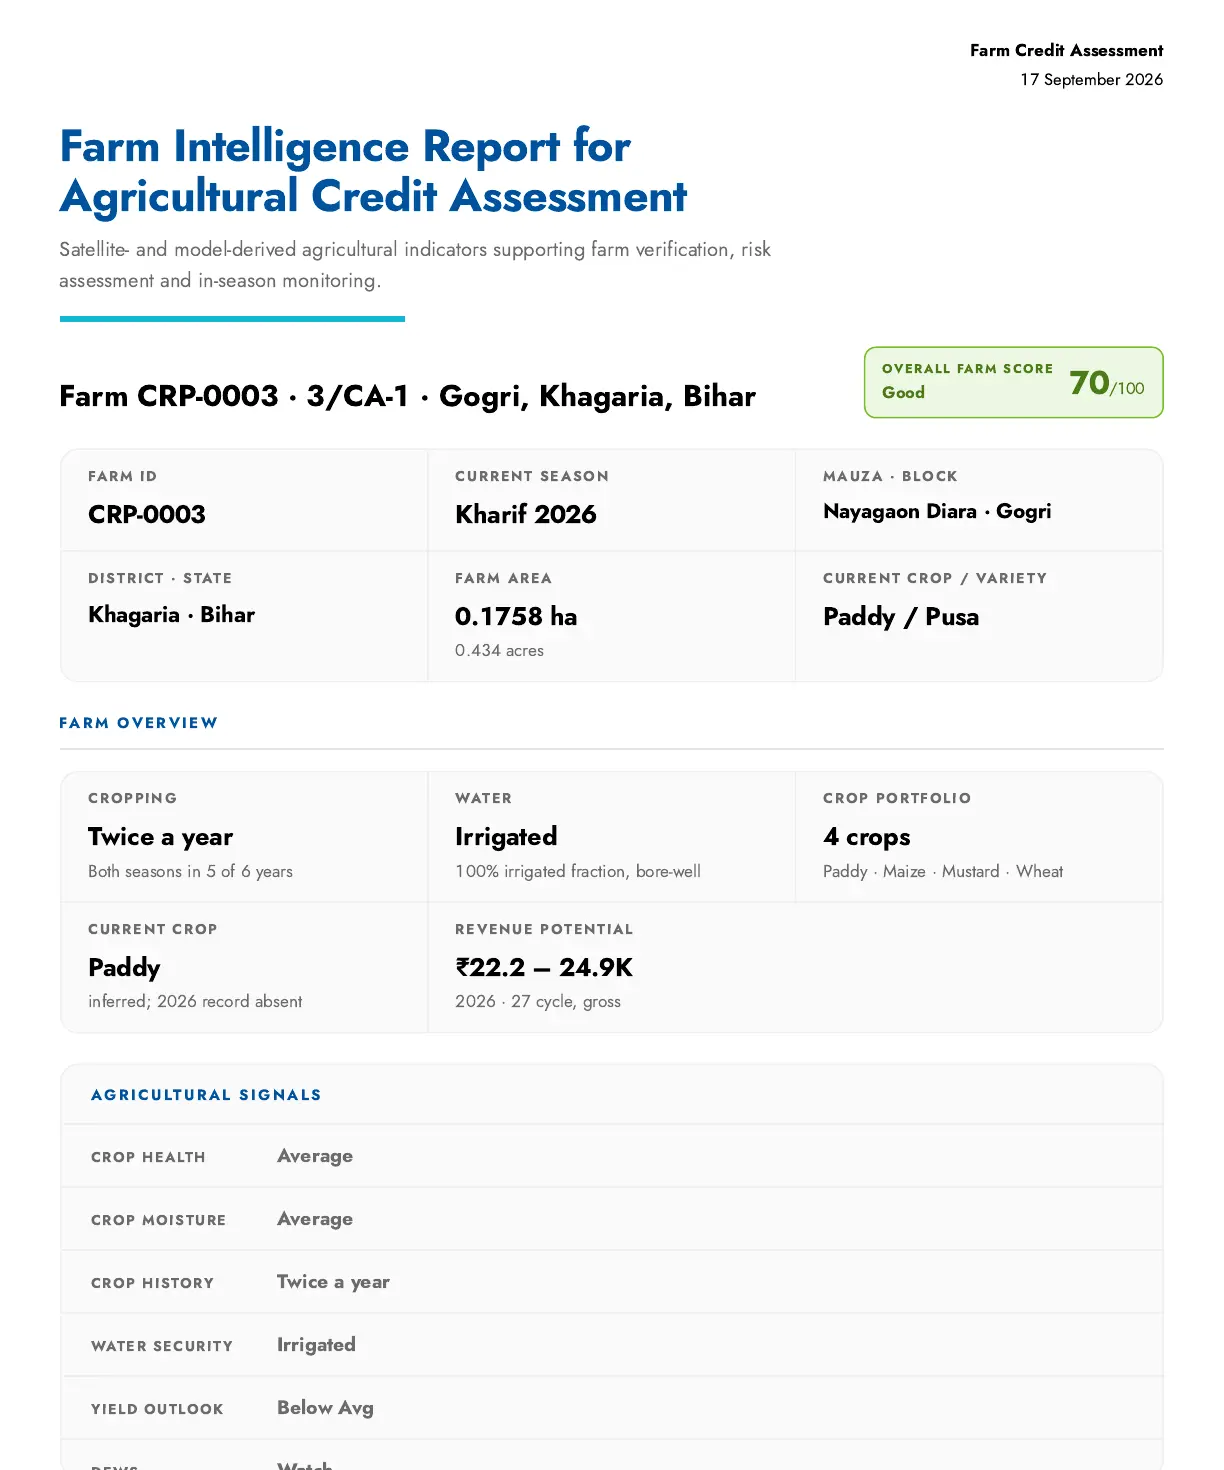
This sample Food-Ag assessment turns plot identity, crop history, water security, yield outlook, revenue potential, growing conditions and model provenance into a reviewable credit file.
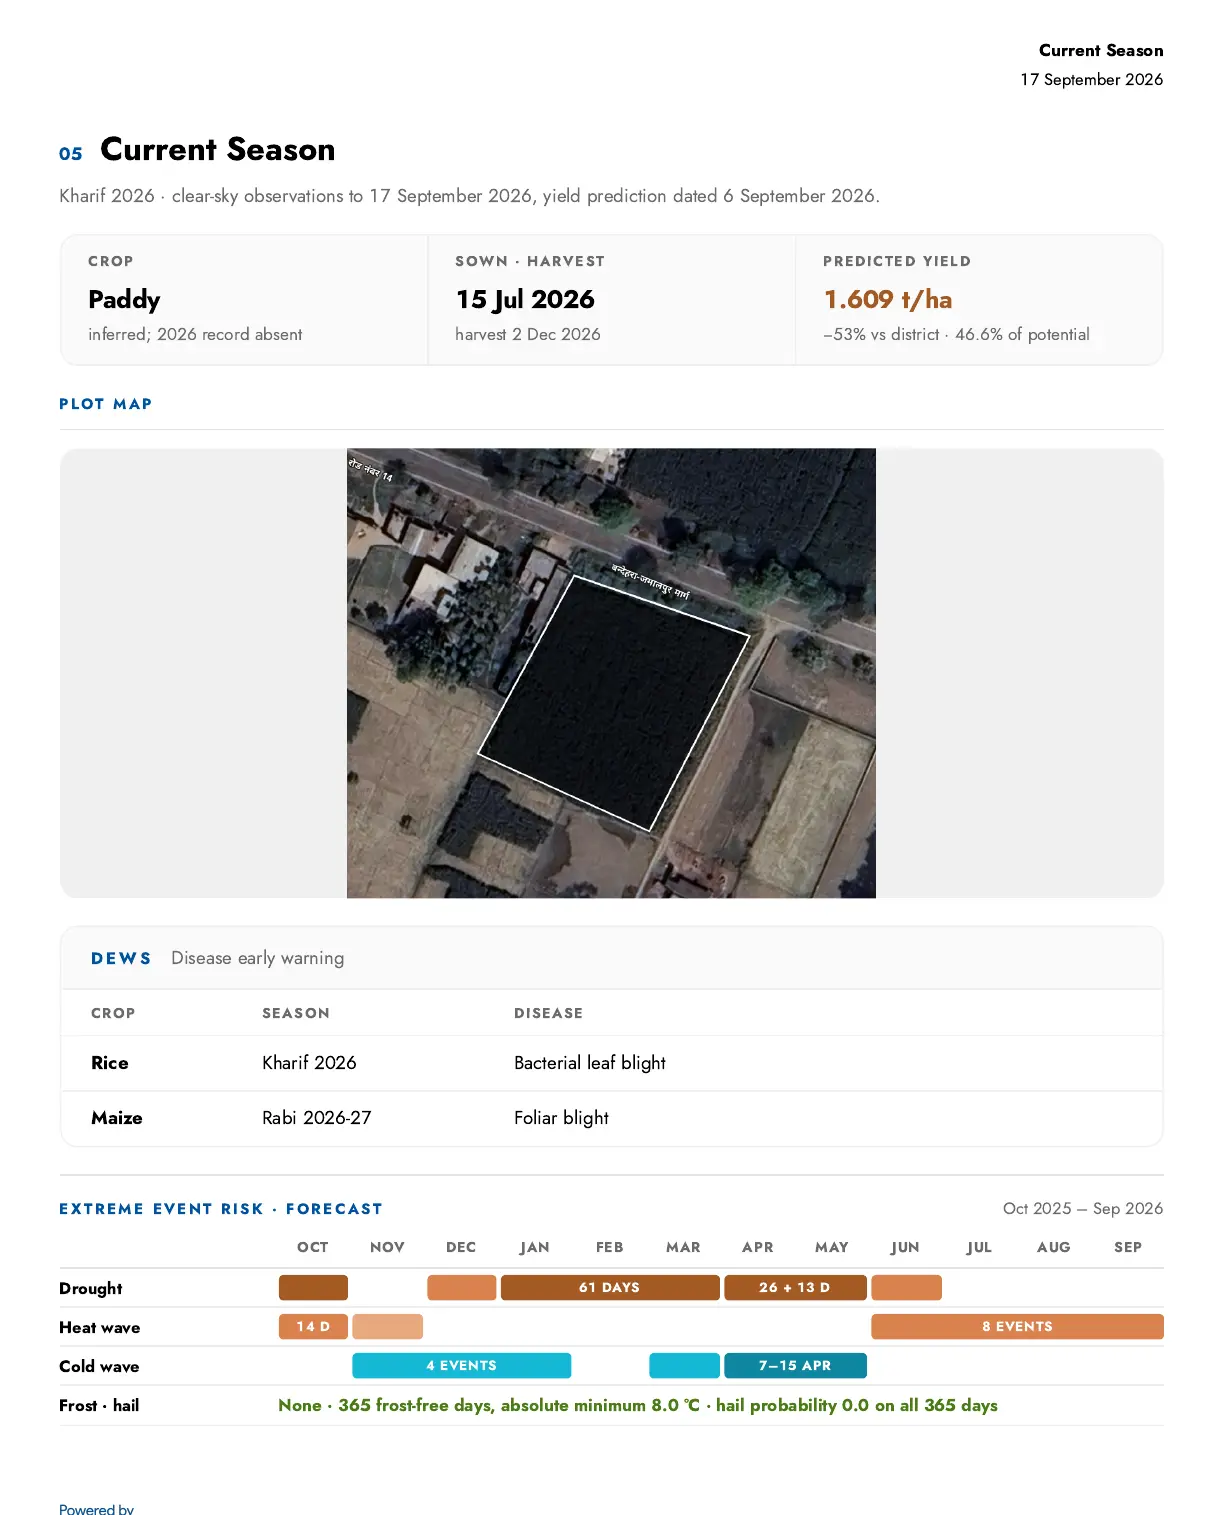
Farm CRP-0003 in Gogri, Khagaria, Bihar is assessed at 0.1758 hectares, with paddy in the current Kharif season and an overall farm score of 70/100 - Good.
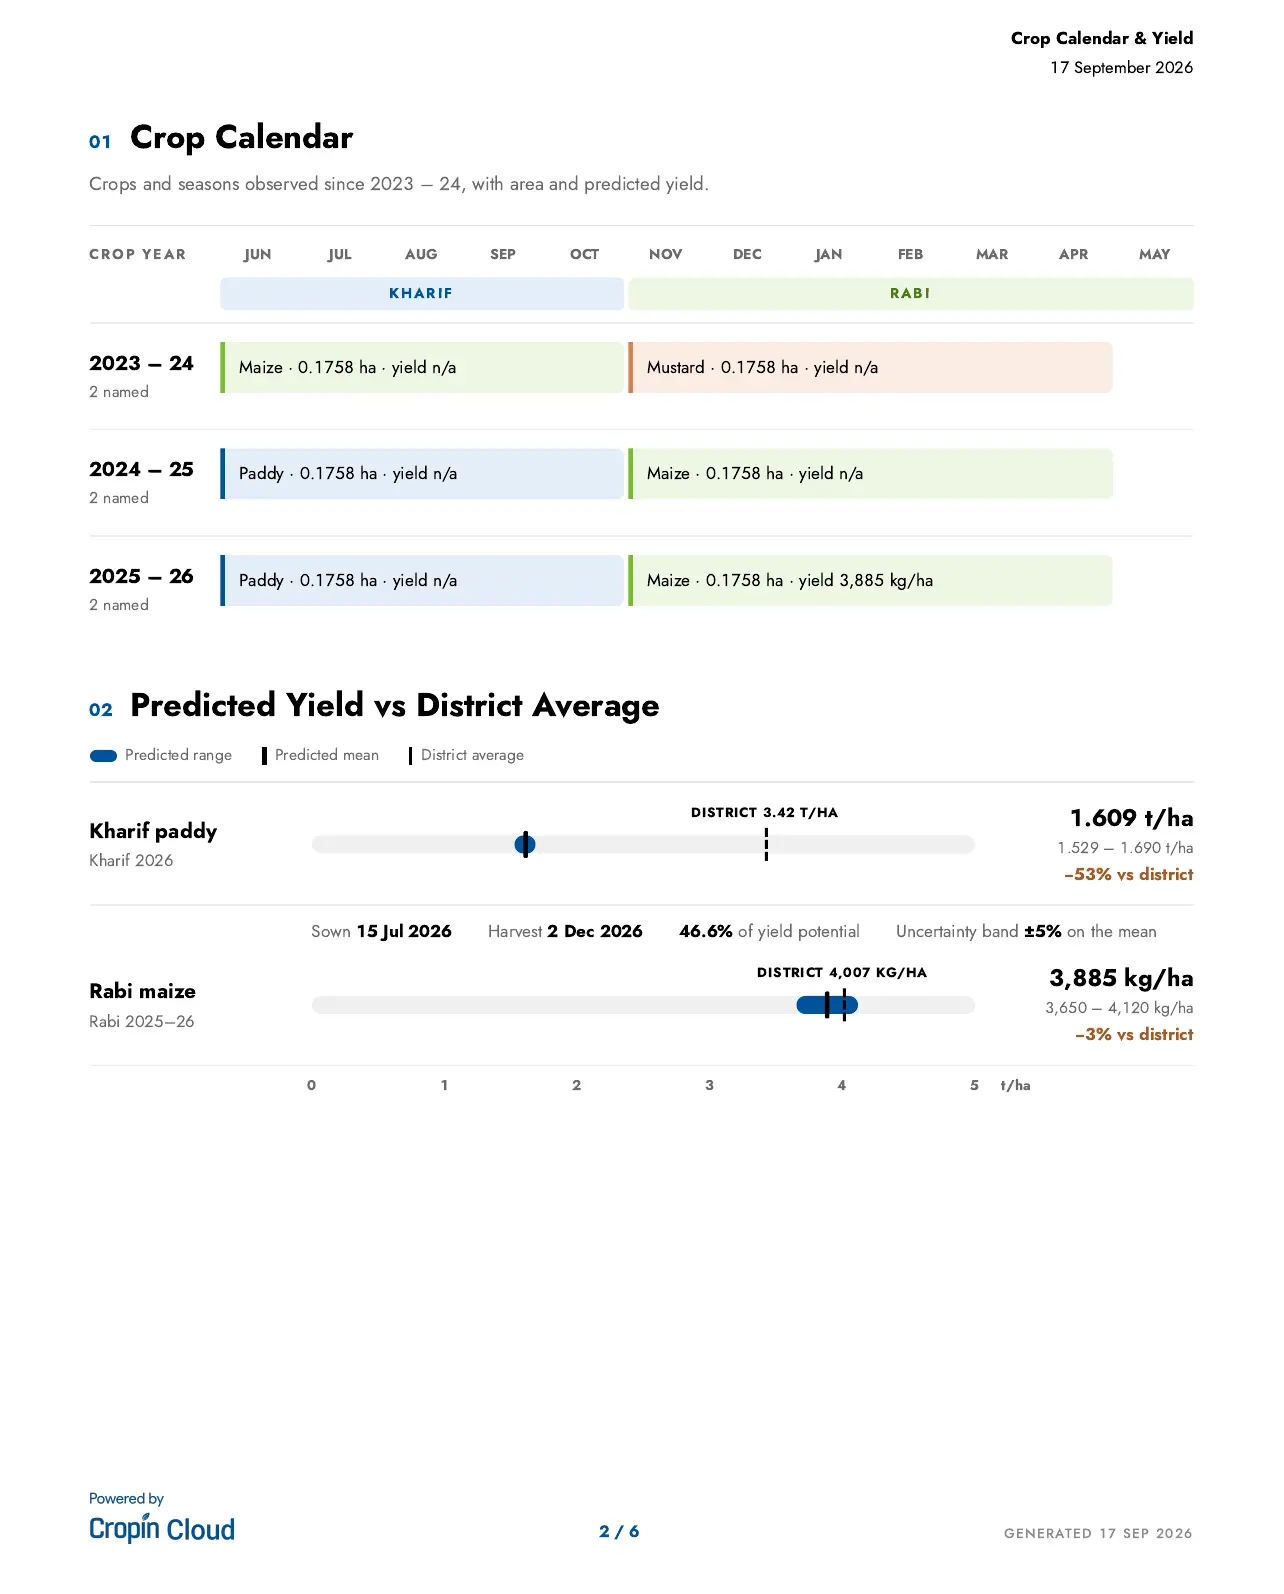
70/100 · GOODThe report connects multi-season crop history with a predicted Kharif paddy range of 1.529-1.690 t/ha, versus a district average of 3.42 t/ha, with a stated uncertainty band.
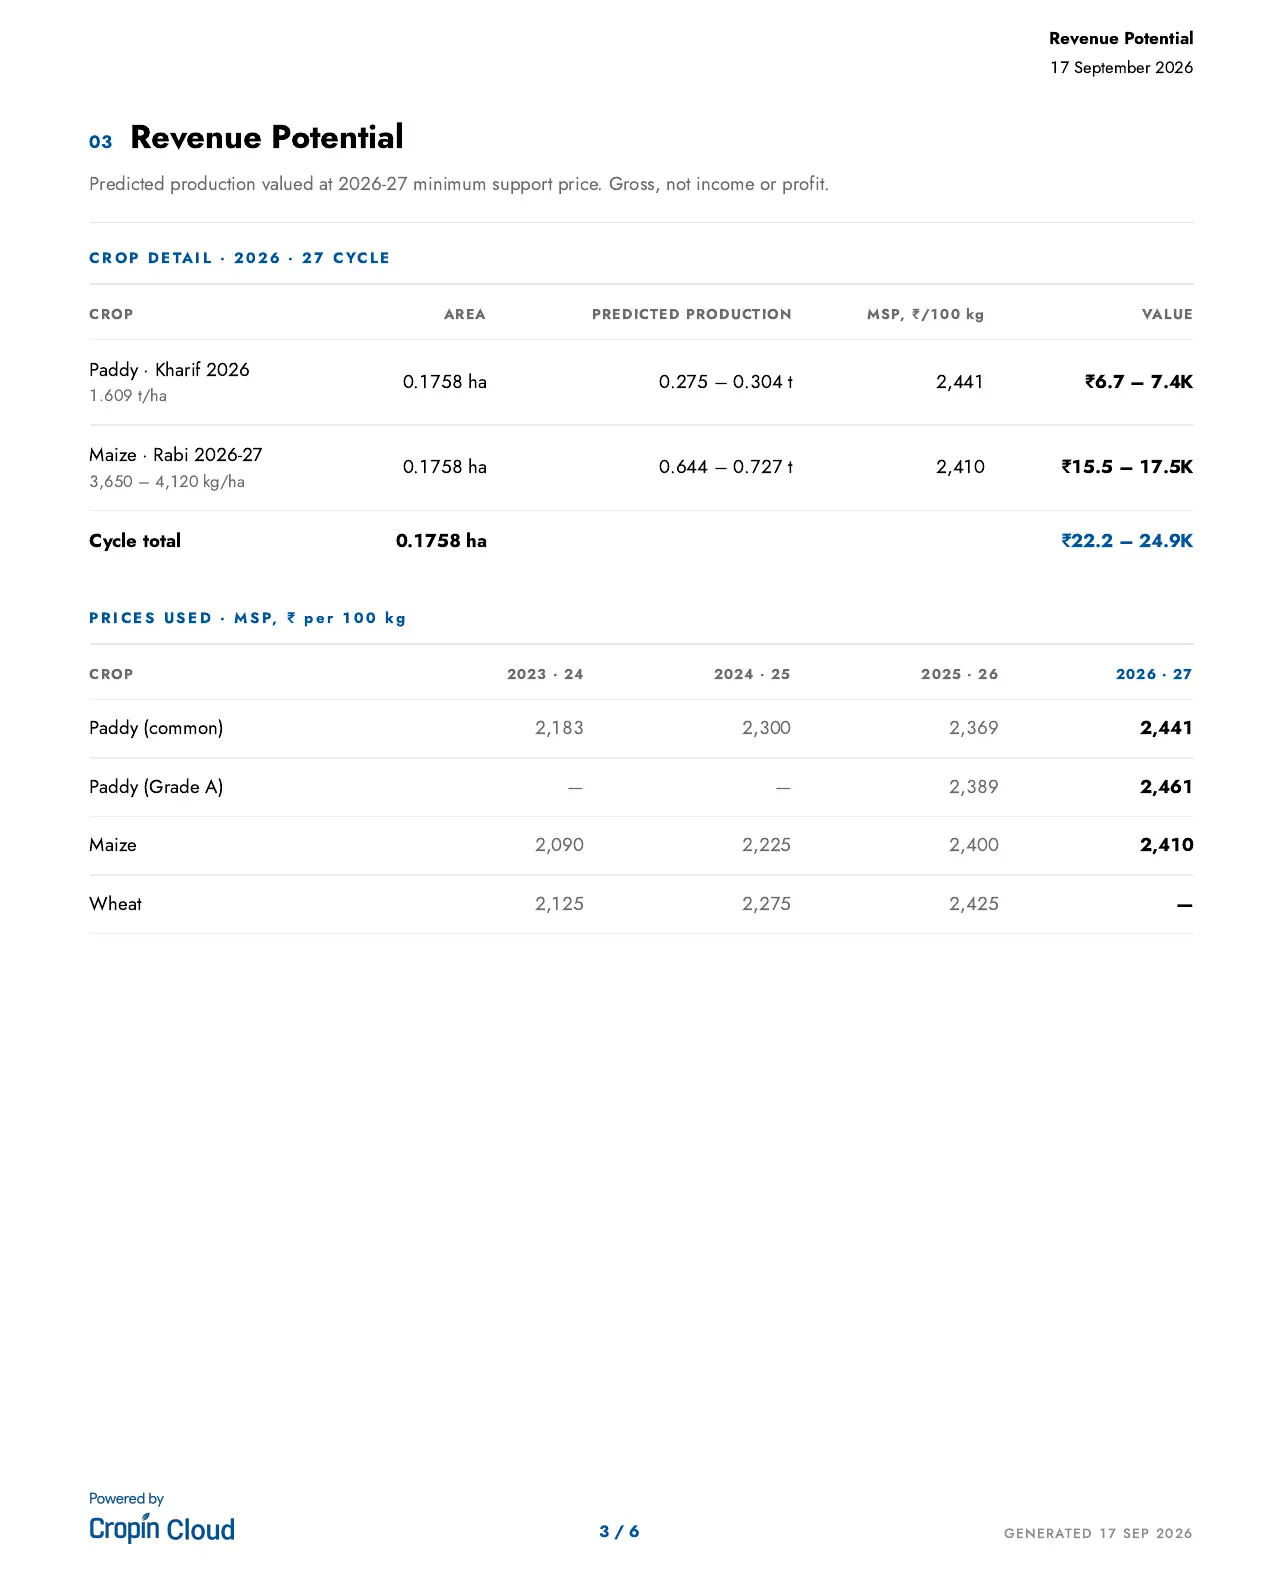
1.529-1.690 T/HAPredicted paddy and maize production is valued using the stated 2026-27 minimum support prices, producing a cycle-level gross value range of ₹22.2-24.9K.
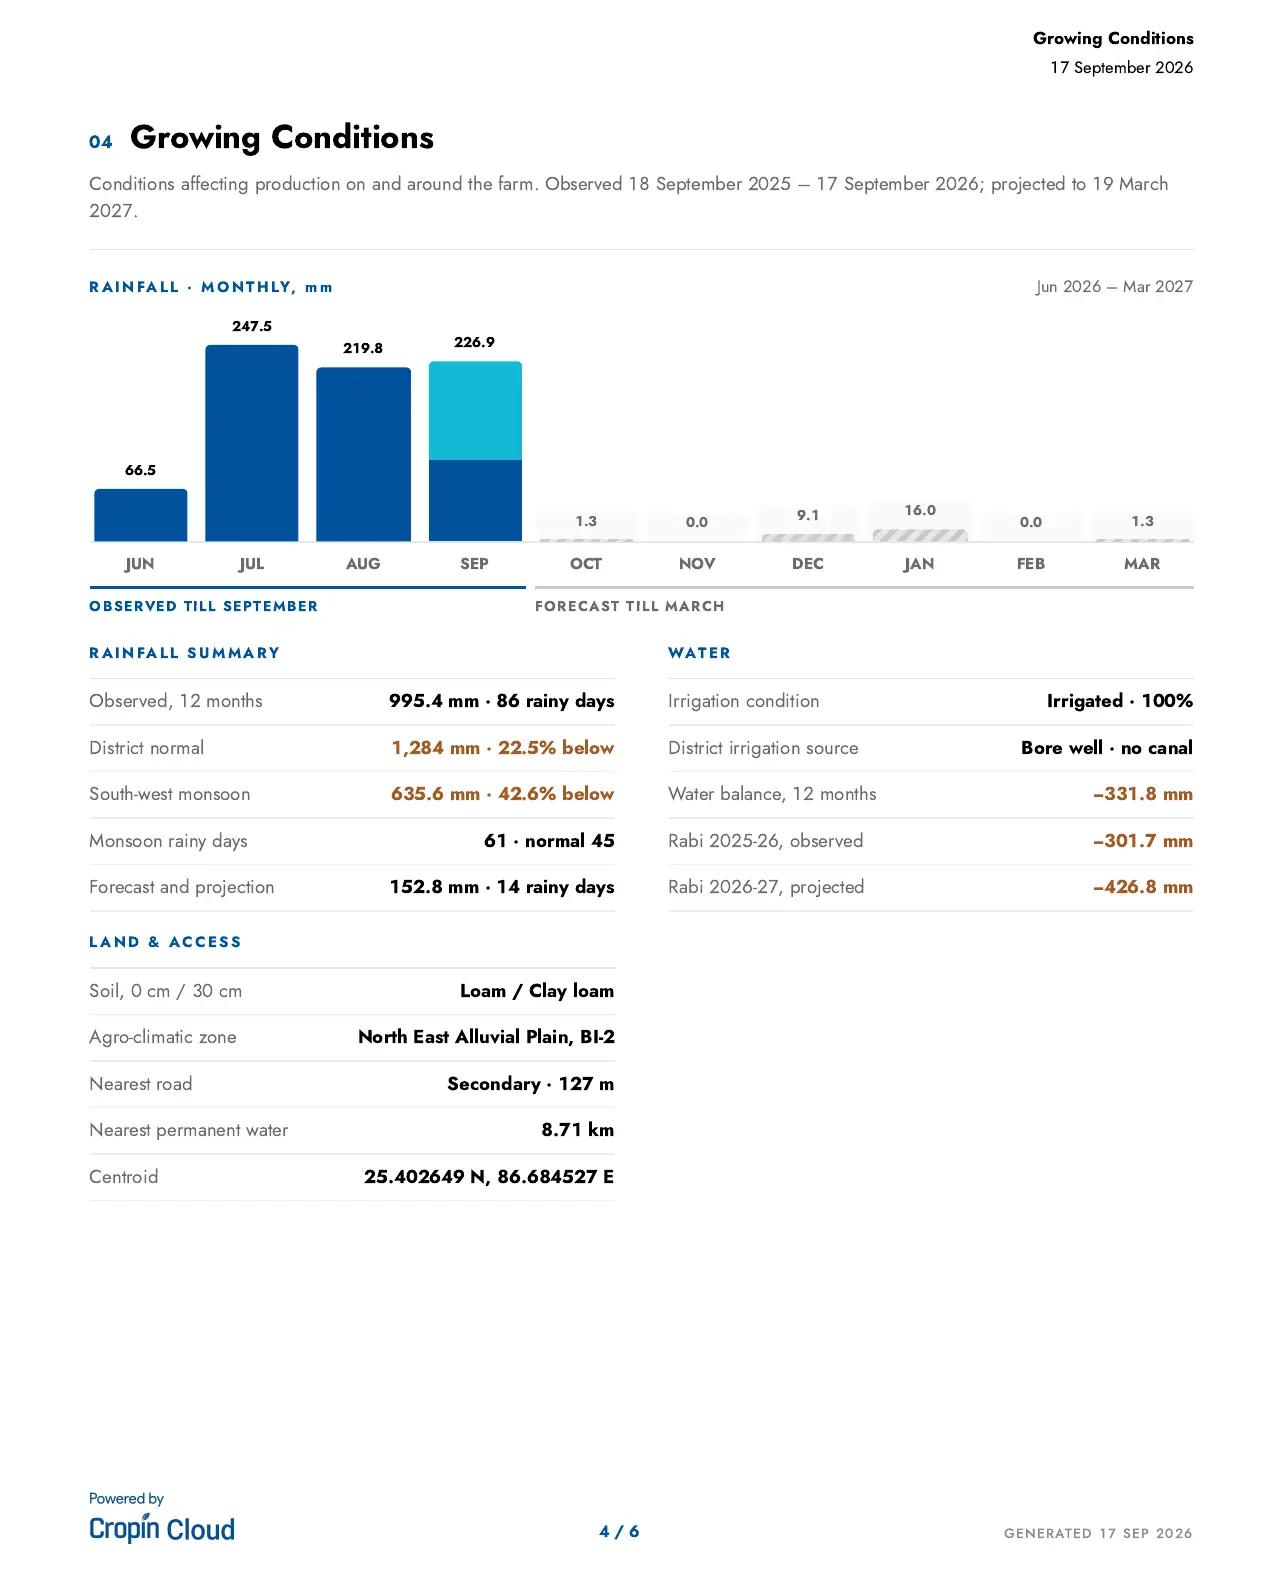
₹22.2-24.9K · GROSSObserved rainfall, monsoon departure, irrigation source, water balance, soil, agro-climatic zone and road access place the farm's production outlook in physical context.
100% IRRIGATEDSowing and harvest timing, plot evidence, disease early warning and extreme-event exposure support monitoring after origination - not only a one-time decision.
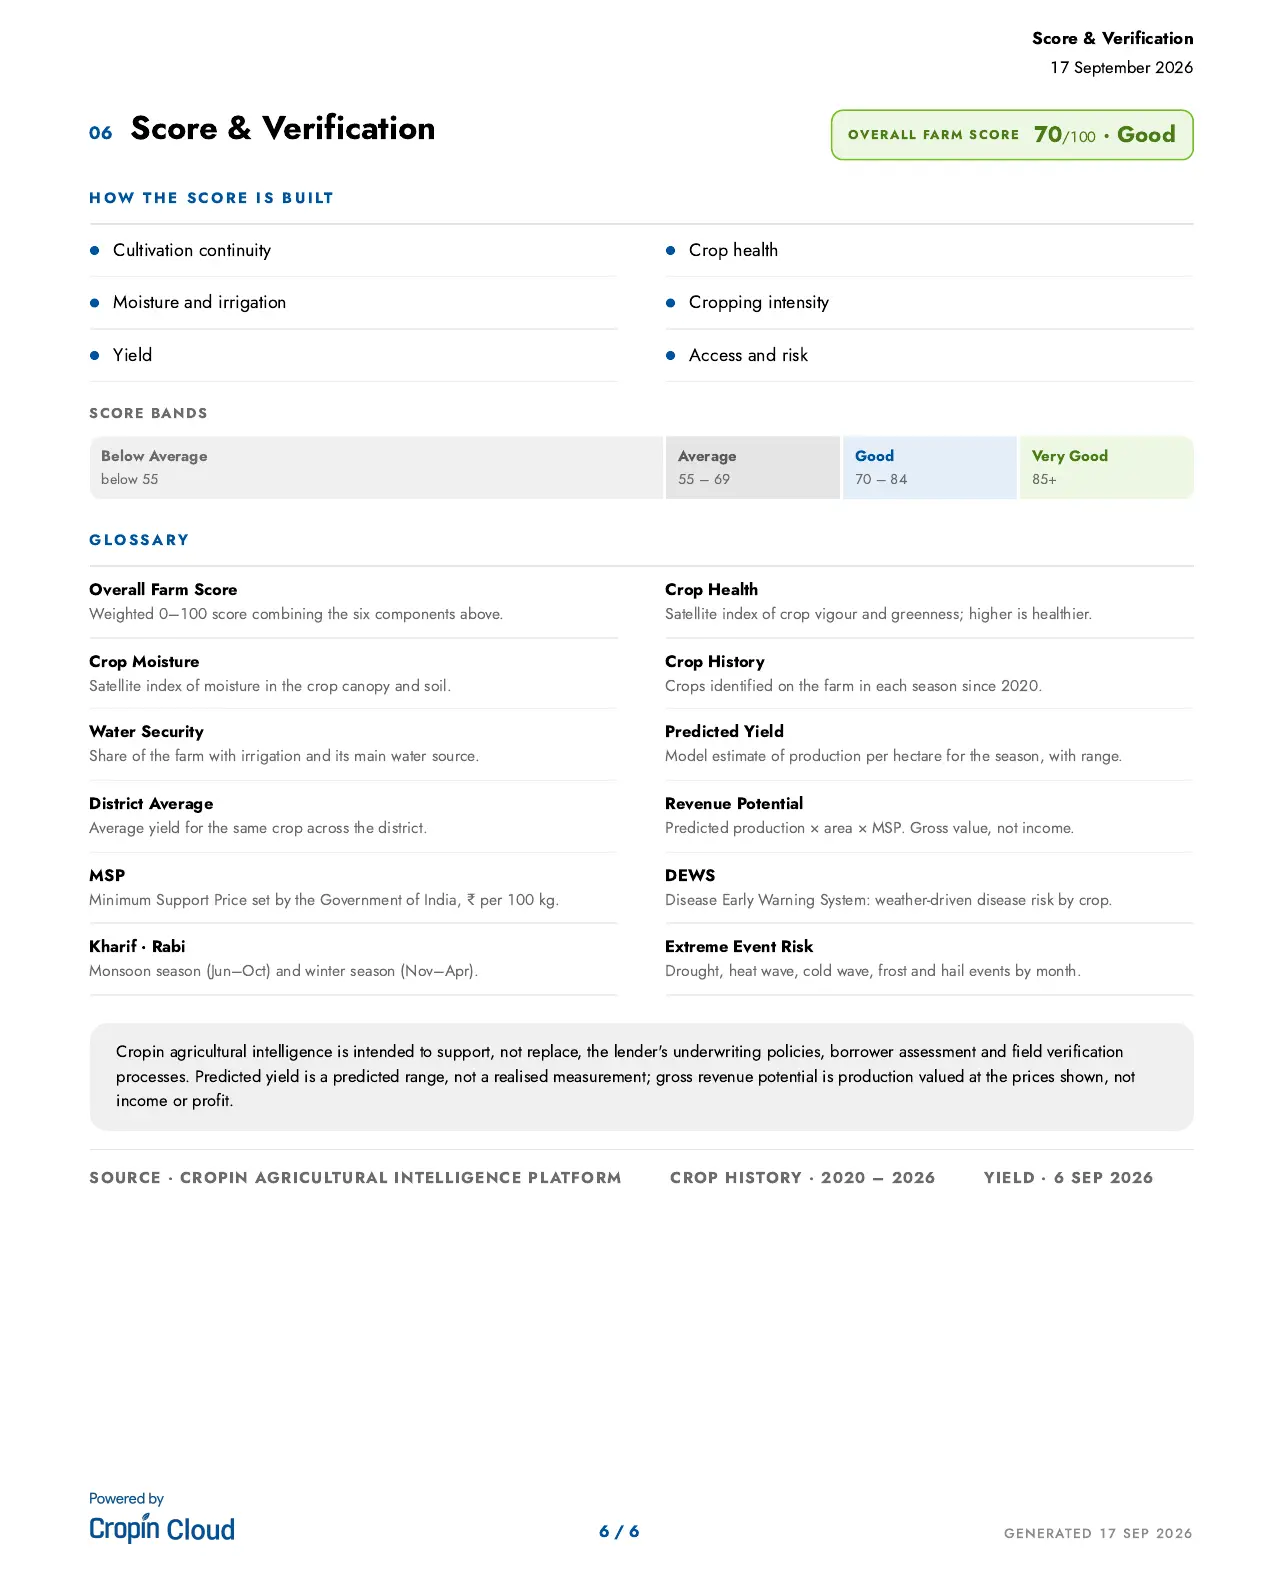
DEWS · CLIMATE RISKThe report exposes the score components, bands, definitions, model dates and provenance so a lender can review the evidence behind the assessment.
6 SCORE COMPONENTS02 / IN PRACTICE · ORBITAI
Move beyond a static farm score. OrbitAI helps credit teams monitor regional portfolios, test downside scenarios and assess expansion opportunities using verified physical-world intelligence.
Farm identity, production potential and explainable evidence.
Concentration, borrower stress and in-season warning signals.
Regional opportunity, underwriting policy and rollout conditions.
For the Chief Risk Officer and Lending Committee.
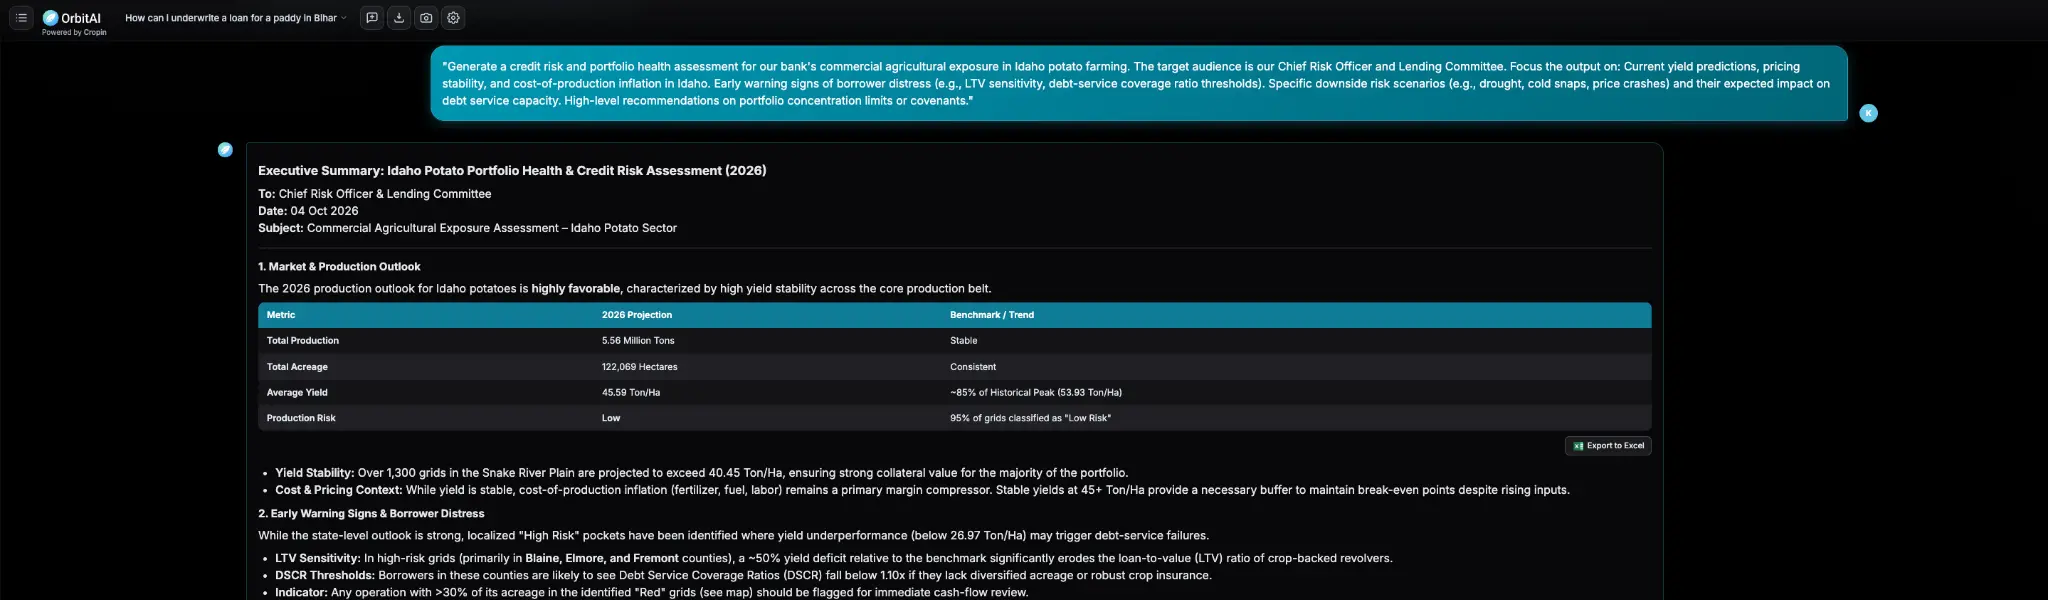
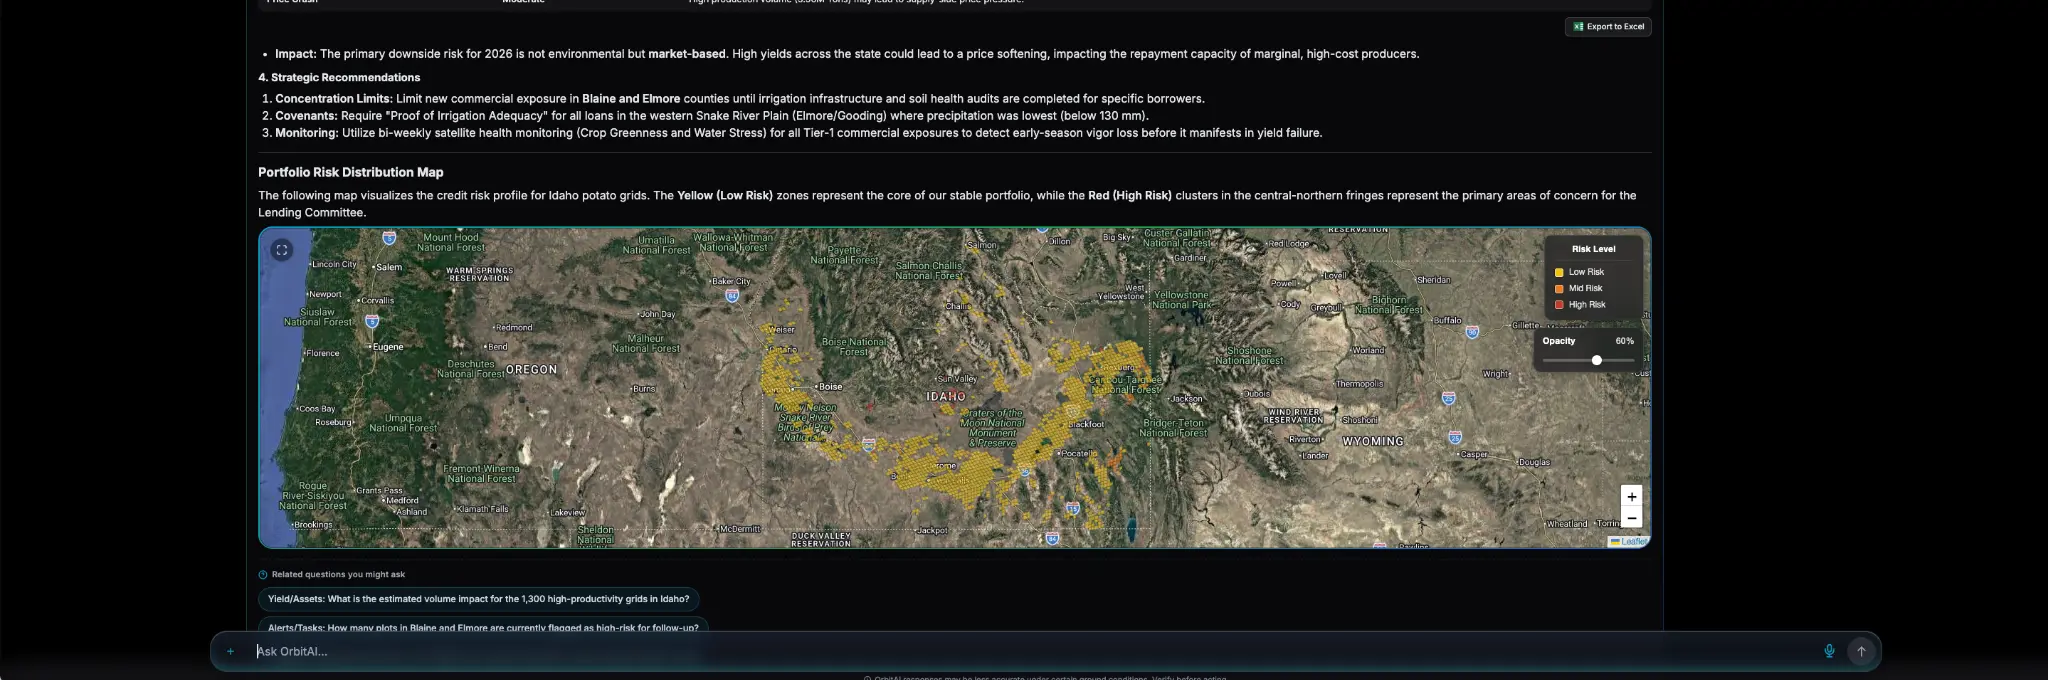
QUESTION TO ORBITAI“Generate a credit risk and portfolio health assessment for our bank's commercial agricultural exposure in Idaho potato farming. Focus on yield predictions, pricing stability, cost inflation, borrower-distress indicators, downside scenarios and portfolio concentration limits or covenants.”
OrbitAI connects acreage, yield stability, pricing and cost inflation to the bank's commercial potato exposure.
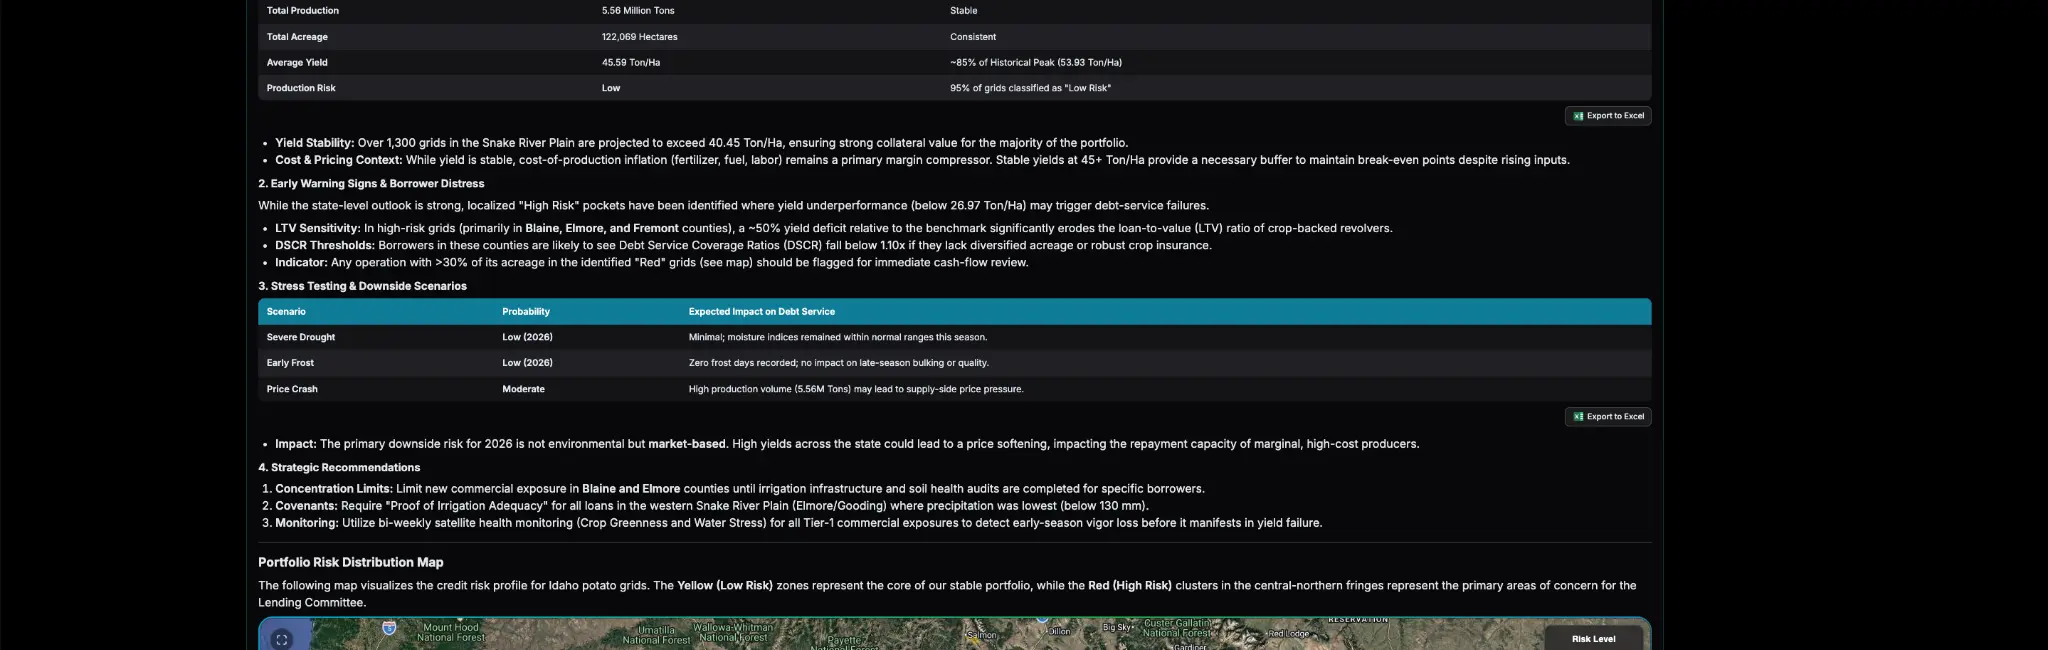
Surface LTV sensitivity, DSCR warning thresholds and the expected impact of drought, frost and price decline.
Locate higher-risk clusters and connect portfolio limits, covenants and monitoring actions to place.
For the Chief Credit Officer and Board of Directors.
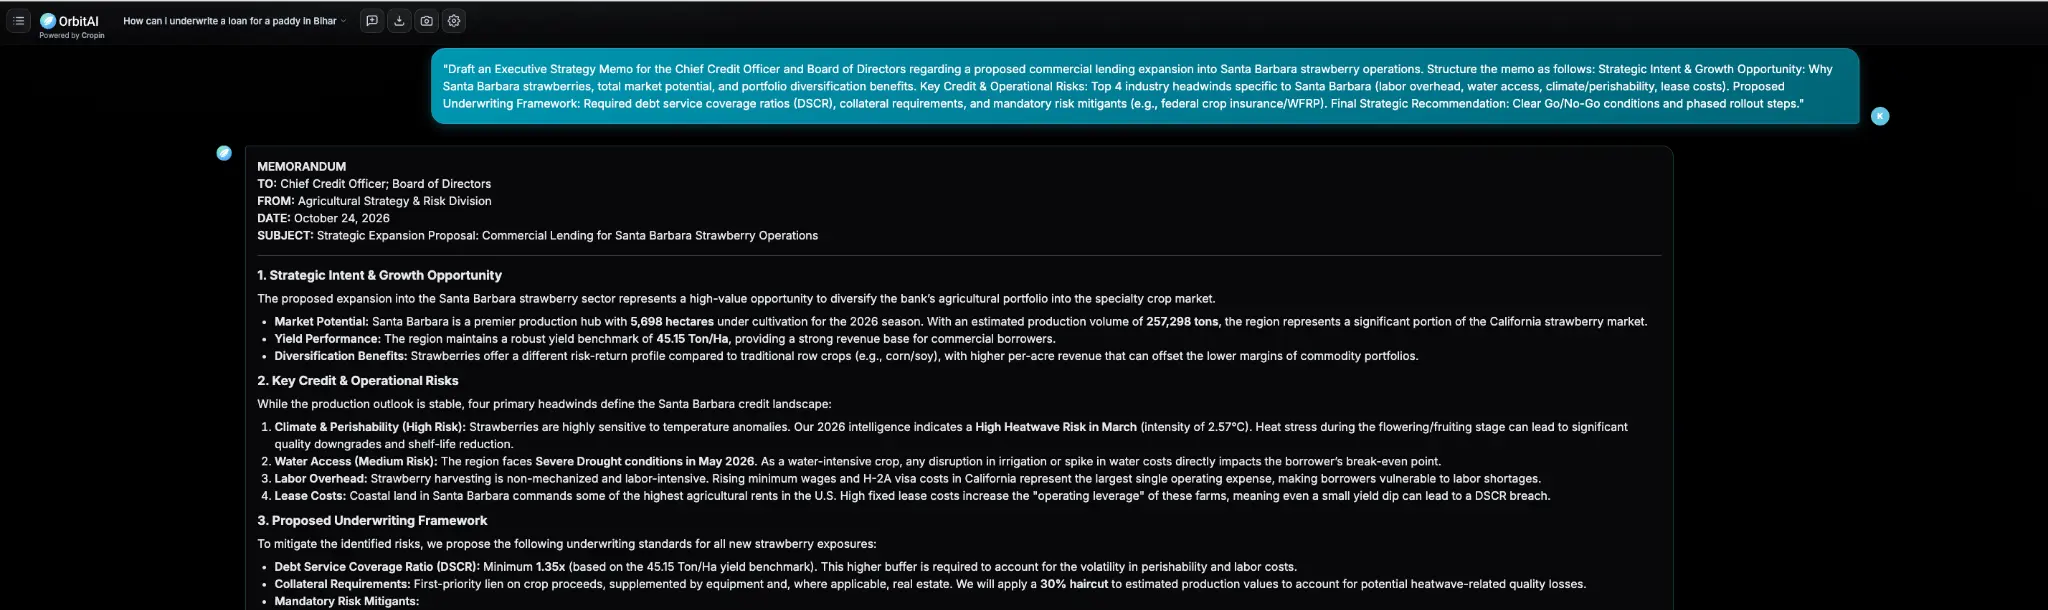
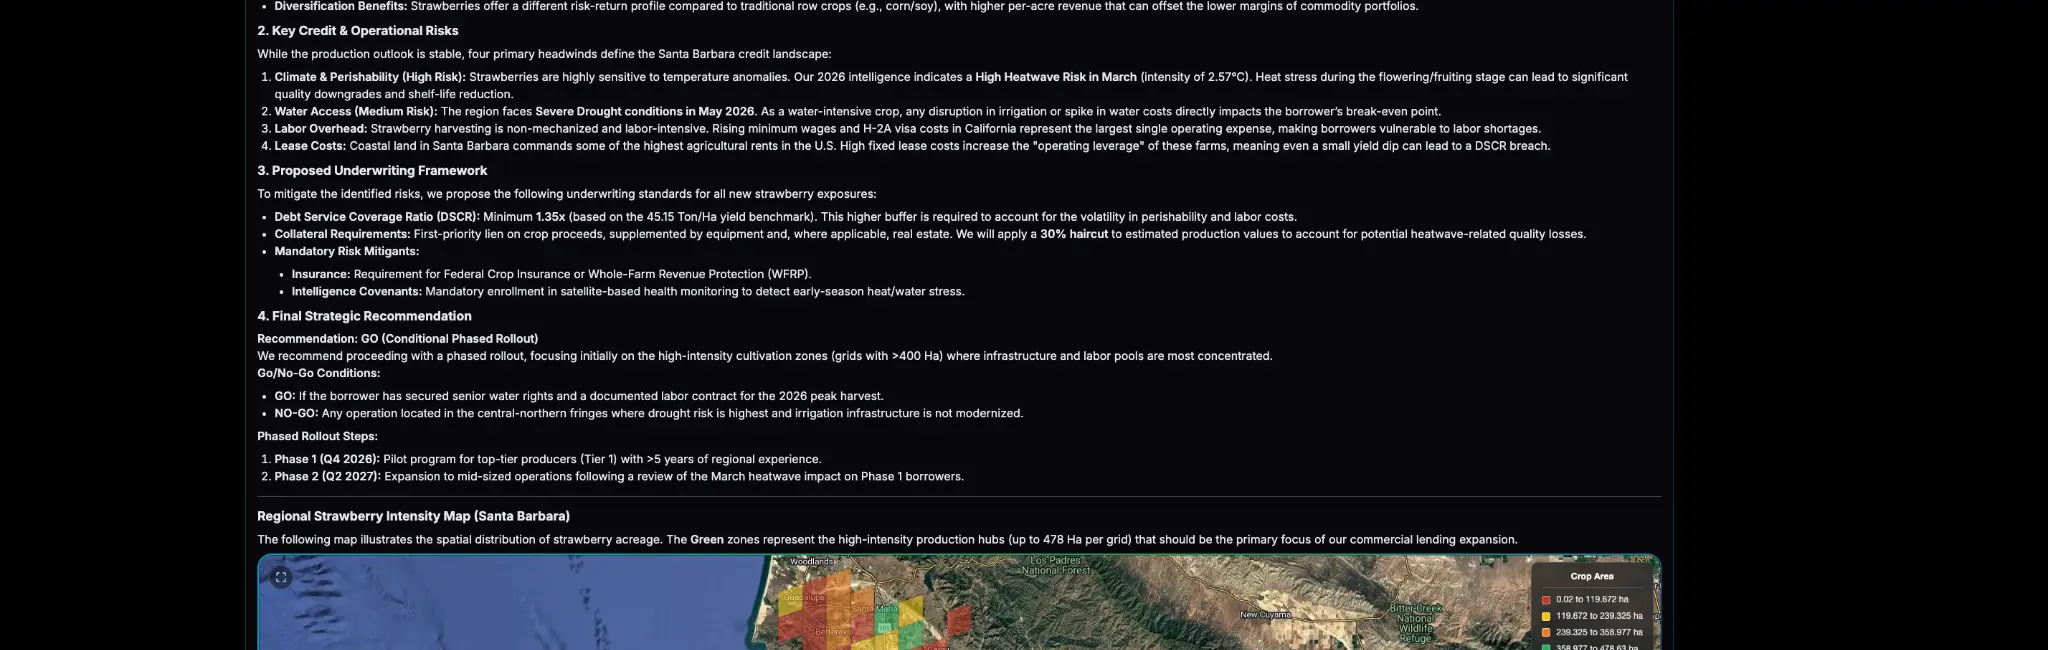
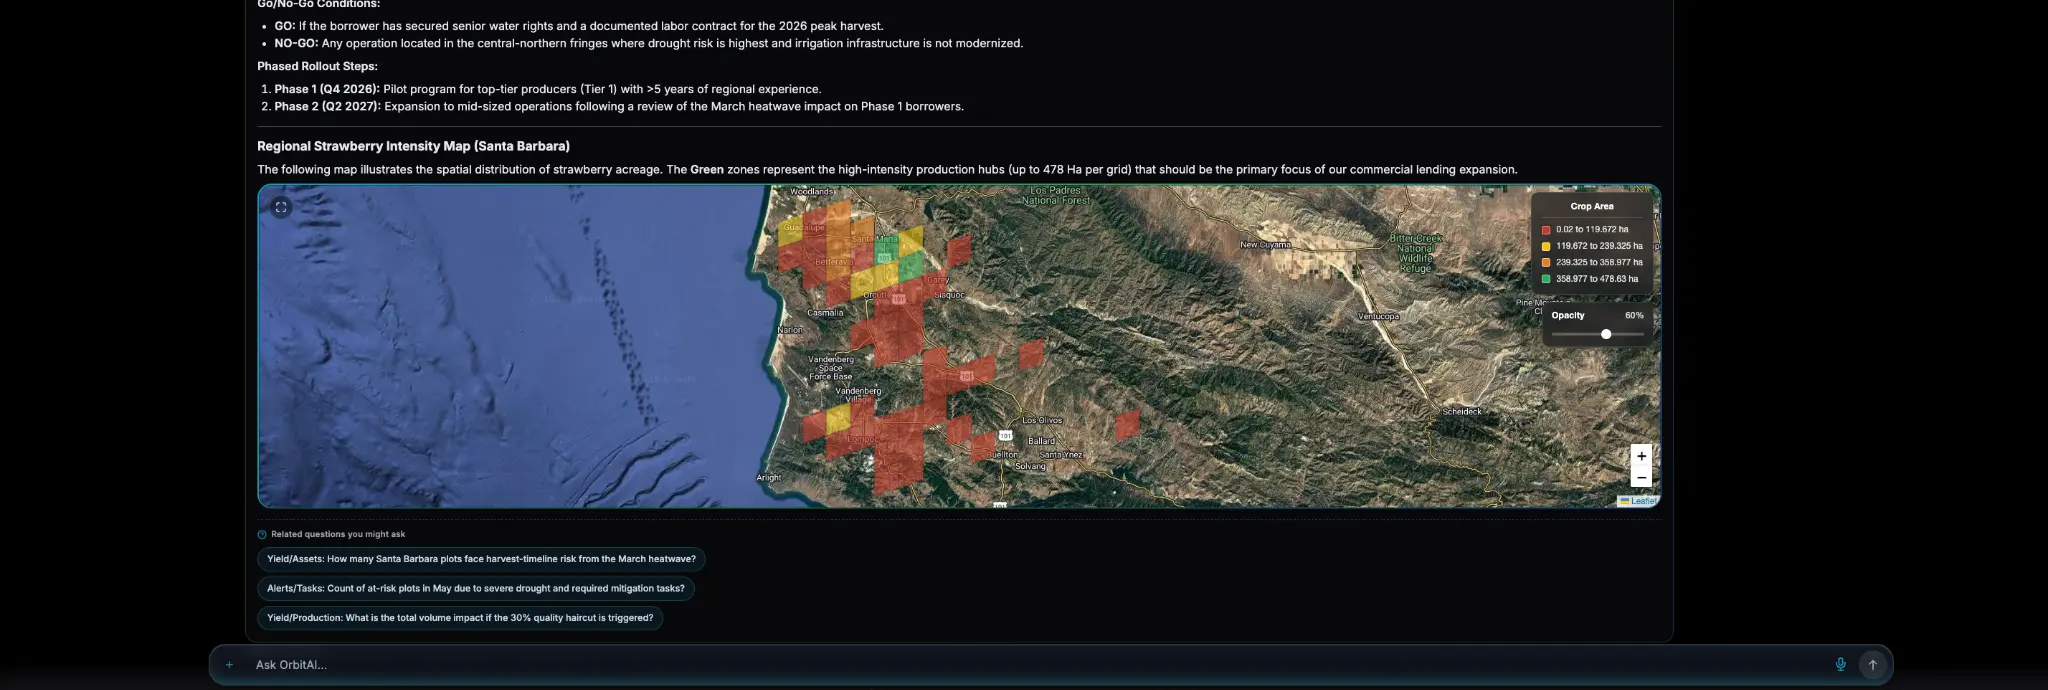
QUESTION TO ORBITAI“Draft an Executive Strategy Memo regarding a proposed commercial lending expansion into Santa Barbara strawberry operations. Assess the growth opportunity, key credit and operational risks, required DSCR and collateral standards, mandatory risk mitigants, Go/No-Go conditions and phased rollout steps.”
Frame the Santa Barbara strawberry opportunity through market potential, production strength and portfolio-diversification value.
Translate labor, water, climate, perishability and lease-cost exposure into DSCR, collateral and risk-mitigation requirements.
Identify production hubs where infrastructure, grower experience and commercial lending opportunity are most concentrated.